Health insurance rarely covers hypnotherapy outright, but reimbursement is possible in specific situations. Coverage depends on your insurer’s policy language, whether a licensed provider documents medical necessity for a diagnosed condition, and your plan type. Billing often runs through CPT code 90880, though most carriers still treat hypnotherapy as experimental.
TL;DR:
- Plans covering hypnotherapy require a diagnosed condition, a licensed clinician, and sometimes an employer benefit rider; Marketplace behavioral coverage alone does not guarantee it.
- Hypnotherapy is billed under CPT code 90880, which Medicare generally does not list as payable; parity law regulates existing benefits but does not mandate coverage.
- Reimbursement is more plausible when a licensed physician or psychologist integrates hypnosis into care for a diagnosed condition, rather than offering standalone wellness sessions.
- HSA, FSA, and HRA funds may cover therapy for a diagnosed condition; keep an itemized invoice and obtain a clinician’s medical necessity letter.
- Before treatment, verify exclusions and preauthorization with member services, request any approval in writing, and assemble diagnosis, treatment plan, credentials, and itemized invoices.
Table of Contents
- How U.S. insurers typically treat hypnotherapy, billing codes, and parity law
- When coverage or reimbursement is possible: clinical settings that get paid
- Step-by-step: checking your plan and improving your odds of reimbursement
- Using HSAs, FSAs, and HRAs to pay for hypnotherapy
- If your claim is denied: a quick appeal checklist
- Our view on navigating insurance questions
- Ready to talk with MindShift Hypnosis?
- FAQ
- Sources
How U.S. insurers typically treat hypnotherapy, billing codes, and parity law
Most major carriers classify hypnotherapy as experimental, investigational, or part of complementary and alternative medicine, a category insurers exclude by default regardless of diagnosis. Aetna’s own clinical policy bulletin on hypnosis places hypnotherapy in this experimental category and states it is typically denied unless it meets specific medical necessity criteria and is performed by a licensed professional. UnitedHealthcare’s complementary and alternative medicine policy lists hypnotism among services generally excluded unless a member’s employer purchased it as a supplemental benefit.
Billing for hypnotherapy sessions typically uses CPT code 90880. Medicare’s coverage materials generally omit 90880 from payable codes, so reimbursement through Medicare is unlikely in routine circumstances.
Federal parity law adds a layer of confusion. It requires that when a plan offers mental health benefits, those benefits get treated no less favorably than medical or surgical benefits in terms of copays, visit limits, and prior authorization rules. It does not require a plan to cover every specific therapy. The American Psychological Association’s parity guidance makes this distinction clear: parity governs how existing benefits are administered, not which therapies must be included.
A few patterns show up across most plans:
- Hypnotherapy is frequently grouped with acupuncture and biofeedback under complementary medicine exclusions.
- Plans that do cover it almost always require a diagnosed condition and a licensed clinician.
- Employer-sponsored plans vary more than Marketplace plans because employers can add or remove specific benefit riders.
Marketplace plans must include behavioral health treatment as an essential health benefit, according to Healthcare, but that requirement covers psychotherapy and counseling broadly. It does not guarantee hypnotherapy specifically, since plan design and state rules still vary.
When coverage or reimbursement is possible: clinical settings that get paid
Reimbursement happens most often inside integrative medicine clinics and supervised clinical hypnosis programs rather than standalone wellness practices. These settings share a few features that make insurers more willing to pay:
- A licensed clinician, often a physician or psychologist, oversees or delivers the hypnosis component.
- The treatment plan ties directly to a diagnosed condition such as chronic pain, anxiety, or an eating disorder.
- Sessions are billed within a broader medical visit rather than as a stand-alone alternative therapy.
A feasibility study of clinical hypnosis in an outpatient integrative medicine clinic found that insurer reimbursement did occur for a subset of patients, with reimbursement occurring among a subset of enrollees. That figure reflects one specific clinic-based group hypnosis model embedded in a larger medical practice, not a typical outcome for an independent hypnotherapist’s office.
The lesson from that study is not that insurance commonly pays for hypnotherapy. It is that a documented, clinically integrated program with a named diagnosis and a credentialed provider stands a measurably better chance than an uncoordinated referral. Complementary and alternative medicine exclusions still apply by default, so getting paid usually requires positioning the service as treatment for a specific medical condition rather than general wellness.
Step-by-step: checking your plan and improving your odds of reimbursement
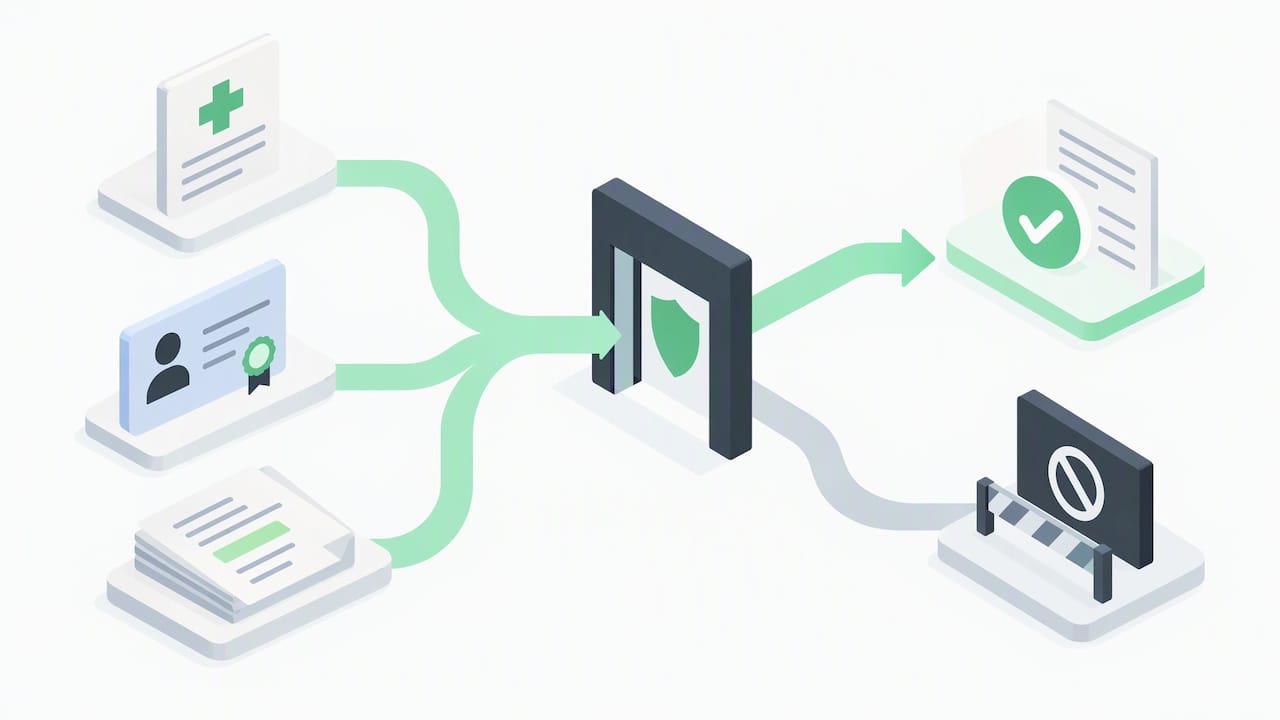
Before booking, a short review of your plan documents saves time and prevents surprise bills.
- Pull your Evidence of Coverage or Schedule of Benefits and search for “hypnosis,” “hypnotherapy,” or “complementary and alternative medicine” to see how your plan classifies it.
- Call member services and ask three specific questions: is hypnotherapy covered under any circumstance, does it require preauthorization, and are there in-network providers who bill it as a covered service.
- If you have employer coverage, ask HR whether the plan includes a complementary medicine rider, since this varies by employer even within the same insurer.
- Request a referral or preauthorization in writing if your plan requires one, since verbal approval rarely survives a claims audit.
- Collect documentation before your first session: a diagnosis from a physician or licensed mental health provider, a written treatment plan, your hypnotherapist’s license and credentials, and itemized invoices with CPT codes.
- Submit out-of-network claims using your plan’s standard reimbursement form, attaching the diagnosis, treatment plan, and itemized invoice together.
Pro Tip: Ask your hypnotherapist for a treatment plan that explicitly names your diagnosed condition before your first session, since retroactive documentation is far harder to get approved.
Using HSAs, FSAs, and HRAs to pay for hypnotherapy
Tax-advantaged accounts offer a more reliable path than insurance reimbursement for many patients. The IRS guidance on medical expenses states that therapy treating a diagnosed medical condition qualifies as an eligible medical expense for HSA, FSA, and HRA reimbursement when properly documented.
Most plan administrators ask for similar paperwork:
- A letter of medical necessity from a physician or licensed mental health provider naming the diagnosed condition.
- An itemized invoice from the hypnotherapist showing dates, fees, and services rendered.
- Proof that the provider holds a relevant professional license.
Save every invoice as you go. If your HSA or FSA administrator flags the claim, a physician’s letter connecting the sessions to a diagnosed condition is usually the deciding document.
If your claim is denied: a quick appeal checklist
Denials usually come down to one of three reasons: the insurer classifies hypnotherapy as experimental or not medically necessary, the documentation is incomplete, or the provider isn’t credentialed in a way the plan recognizes. A denial is not always final.
- Request the full written denial letter, which states the specific policy exclusion or missing information the insurer cited.
- Ask your treating clinician for a letter of medical necessity that names your diagnosis and expected, measurable treatment goals.
- File an internal appeal with your insurer, attaching the clinician letter, treatment plan, and itemized session notes.
- If the internal appeal fails, request an external review, or contact your state insurance department if you have an individual or small-group plan.
- For employer-sponsored plans governed by ERISA, contact your plan administrator directly, since state insurance departments often have limited authority over those plans.
- If the appeal still fails, consider paying out-of-pocket and submitting the expense to an HSA or FSA instead, since the IRS standard is separate from any single insurer’s coverage decision.
Our view on navigating insurance questions
We build every session around a customized treatment plan, whether working with individuals addressing anxiety, couples working through relationship strain, or athletes preparing for competition. Our licensed providers offer both in-person and online sessions, and we often collaborate alongside a client’s existing physician or therapist rather than replacing that care, a model we describe in more detail when we talk about combining hypnotherapy with traditional healthcare.
When a client is pursuing reimbursement, support is provided to document the treatment plan and session notes clearly, though no promise of a specific coverage outcome is made, since that decision always sits with the insurer.
— Rachael
Ready to talk with MindShift Hypnosis?
We offer Hypnosis Only, Hypnosis Life Coaching, and fully remote sessions for clients who want flexibility without sacrificing a personalized plan.
Whether you’re exploring treatment for anxiety, trauma, or performance goals, we document your sessions clearly enough to support a reimbursement claim or HSA submission. Visit our services page to see current session types and book a consultation.
This article is general information, not a substitute for advice from a qualified doctor. Consult a qualified healthcare professional about your own circumstances before acting on anything here.
FAQ
Is hypnotherapy ever covered by health insurance?
Coverage is uncommon but not impossible. It happens most often in integrative medicine clinics where a licensed clinician documents medical necessity for a diagnosed condition, as shown in a clinical hypnosis feasibility study that found insurer reimbursement occurred for a subset of patients.
What CPT code is used for hypnotherapy billing?
Hypnotherapy sessions are typically billed under CPT code 90880. Medicare generally does not list this code as payable, and many commercial insurers, including Aetna, treat claims under it as experimental.
Does mental health parity law require coverage of hypnotherapy?
No. Federal parity law requires that mental health benefits, when offered, be administered on equal terms with medical benefits, according to APA parity guidance. It does not force any plan to add hypnotherapy as a covered service.
Can I pay for hypnotherapy with my HSA or FSA?
Yes, if the sessions treat a diagnosed medical condition and you have proper documentation. The IRS treats qualifying therapy as an eligible medical expense for HSA, FSA, and HRA reimbursement.
What should I do if my hypnotherapy claim is denied?
Request the written denial letter to see the exact reason, then gather a clinician’s letter of medical necessity along with your treatment plan and session notes. File an internal appeal first, and escalate to an external review or your state insurance department if that appeal fails.
Sources
- Aetna clinical policy bulletin on hypnosis/hypnotherapy
- Healthcare
- Clinical hypnosis for chronic pain in outpatient integrative medicine: implementation and reimbursement data
- UnitedHealthcare complementary and alternative medicine provider policy (CA example)
- IRS FAQs: medical expenses, HSAs, FSAs, and eligible therapy expenses
- APA parity guidance and explanation